
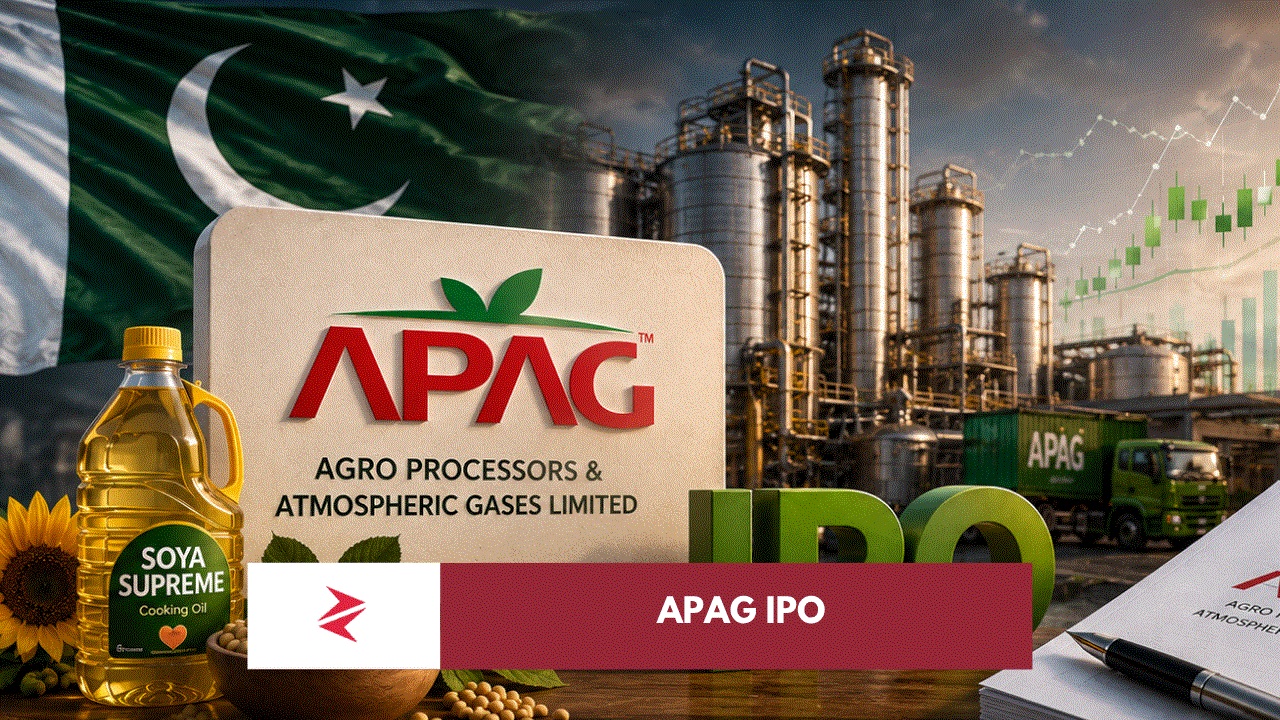
Pakistan’s IPO market has another serious test in front of it. Agro Processors & Atmospheric Gases Limited, better known to consumers through its Soya Supreme business, has completed the institutional book-building stage of its initial public offering and now moves into public subscription on September 3 and 4, 2026. Unlike an IPO limping into the retail stage with institutions sitting on their hands, APAG arrives with a considerably stronger signal: the book-building portion was reportedly oversubscribed 1.84 times and the strike price was discovered at Rs33 per share, only Rs1 above the Rs32 floor price. That combination tells us two things at once. There was genuine demand for the issue, but institutional investors were not prepared to chase the valuation anywhere near the Rs44.80 upper end of the permitted price band.
That distinction matters.
An IPO being oversubscribed is not, by itself, an instruction to buy it. Neither is a glossy consumer brand, a familiar bottle of cooking oil on the supermarket shelf, or a green arrow pointing upward on somebody’s social-media graphic. What matters is what business the investor is buying, how much is being paid for it, what the company intends to do with the new capital, and whether the earnings that supposedly justify today’s valuation can actually materialise tomorrow.
For APAG, there is enough here to make the IPO interesting. There is also enough uncertainty to make blindly chasing it a bad idea.
APAG’s IPO Has Already Passed Its First Market Test
The official Pakistan Stock Exchange APAG offering page confirms that APAG’s listing application has been approved, with PSX approval dated August 7 and SECP approval dated August 11. Book building was scheduled for August 27–28, while public subscription is officially scheduled for September 3–4, 2026. As of the beginning of the public-subscription period, PSX still shows the eventual listing date as pending.
The offer comprises approximately 58.05 million ordinary shares, representing 15% of APAG’s post-IPO paid-up capital. Of these, 75% were earmarked for the book-building portion involving institutional investors and high-net-worth individuals, while the remaining 25% moves to general public subscription.
The reported book-building result is particularly useful because it gives retail investors an actual market-discovered price rather than merely a valuation dreamed up in a spreadsheet.
| IPO Metric | APAG |
|---|---|
| Total shares offered | ~58.05 million |
| Post-IPO capital represented | 15% |
| Book-building allocation | 75% |
| Retail/public allocation | 25% |
| Floor price | Rs32/share |
| Maximum permitted price | Rs44.80/share |
| Discovered strike price | Rs33/share |
| Reported book-building oversubscription | 1.84x |
| Public subscription | September 3–4, 2026 |
| PSX approval | August 7, 2026 |
| SECP approval | August 11, 2026 |
There is an important story hiding inside those Rs32 and Rs33 numbers. Demand was strong enough to oversubscribe the book, yet price discovery stopped almost immediately above the floor. Institutions effectively said: yes, we want the shares; no, we are not going to pay anything close to Rs44.80 for them.
For retail investors, that is arguably healthier than a euphoric book-building exercise racing all the way to the cap. It leaves less speculative froth embedded in the IPO price.
What Exactly Is APAG?
The name “Agro Processors & Atmospheric Gases Limited” sounds considerably more industrial than the business most Pakistanis will recognise. APAG manufactures and markets edible oils, vanaspati, industrial fats, margarine and related food products, with Soya Supreme being its best-known consumer-facing identity.
That brand recognition matters, but investors should be careful about what they infer from it.
APAG operates substantially within an edible-oil processing and refining ecosystem where profitability can be influenced by imported raw-material costs, commodity prices, foreign exchange, refining spreads, energy expenses, working-capital requirements and competitive pricing. This is not automatically the same economic model as a high-margin multinational branded FMCG company merely because a consumer sees the product in a grocery aisle.
That is probably the single most important conceptual distinction in evaluating this IPO.
Where Is the IPO Money Going?
The offering becomes more compelling when we examine why APAG wants fresh capital.
According to the offering information supplied with the IPO, a substantial portion of proceeds is intended for capital expenditure, including plant and machinery, warehousing and storage infrastructure and green-energy investments. The expansion programme is expected to increase refining capacity by roughly one-third, reaching approximately 120,000 tonnes annually.
That is fundamentally different from an IPO whose proceeds simply allow existing shareholders to cash out.
New productive capacity can create additional earnings. Storage infrastructure can improve operating flexibility. Solar and biomass investments can potentially reduce exposure to Pakistan’s notoriously expensive and unpredictable industrial energy environment. Working capital, meanwhile, is particularly important in an industry dealing with commodity inventories and imported inputs.
The investment case therefore rests partly on whether APAG can convert this capital expenditure into higher volumes and, crucially, acceptable returns on that additional capital.
Capacity expansion without margin discipline is merely a larger factory.
Capacity expansion accompanied by stronger volumes, improved energy economics, distribution growth and disciplined working-capital management can create shareholder value.