

























Will Easypaisa or JazzCash Freeze the Account?
No platform can responsibly promise that an account will never be reviewed or restricted.
Under SBP’s new framework, banks and regulated entities must conduct customer due diligence, assess risk, monitor VASP relationships and report suspicious transactions to the Financial Monitoring Unit.
A documented transfer from an authorized provider should be safer than receiving unexplained money from an unknown P2P buyer. It does not eliminate compliance obligations.
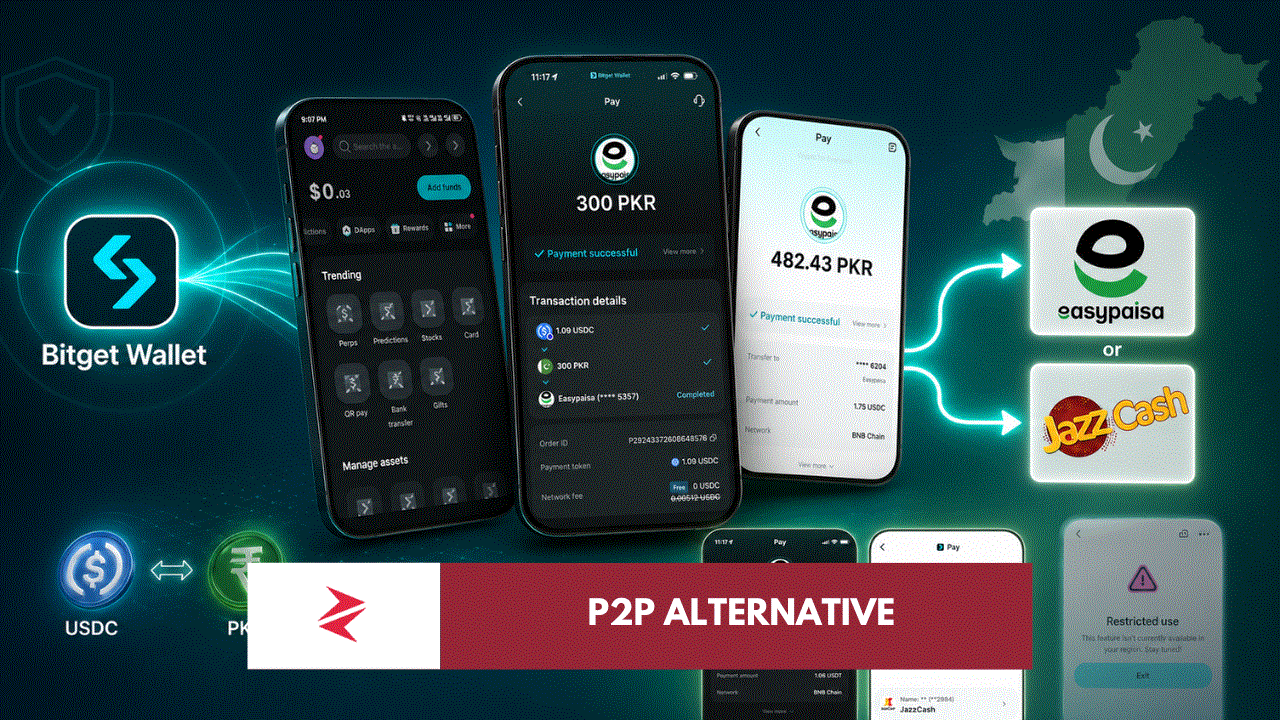
Users should receive funds only into an account held in their own name, retain the Bitget order ID, save the blockchain transaction record and keep screenshots showing the stablecoin amount, PKR quotation, recipient and payment status.
Using another person’s Easypaisa or JazzCash account is not a clever shortcut. It breaks the identity trail and creates an avoidable compliance problem.
Is a PRC Available for This Transfer?
A Proceeds Realization Certificate is not automatically generated whenever foreign-linked value arrives in Pakistan.
SBP rules provide for an electronic PRC when funds are received from abroad through an Authorized Dealer and formally realized through the banking system.
The attached Bitget transactions appear to end as local PKR payments into mobile wallets. That alone does not establish that the recipient received a qualifying inward remittance.
Before treating the transaction as foreign income or remittance, users should ask:
- Who is the legal remitter?
- From which country were the funds remitted?
- Which Authorized Dealer processed the foreign exchange?
- Under which International Transactions Reporting System purpose code was it reported?
- Will the bank or payment institution issue an ePRC?
- Is the payment classified as remittance, asset disposal or local settlement?
No specific SBP purpose code for a retail crypto-to-Easypaisa cash-out was identified in the public material reviewed. Users should therefore not invent a freelance, family-remittance or export-services purpose code merely to obtain documentation.
Misrepresenting the purpose of funds is wrong.
What About Crypto Taxes?
Social-media claims that every non-filer will automatically lose more than 30% are not established by the screenshots or cited regulations.
Likewise, a zero-fee label does not make the proceeds tax-free.
The relevant tax treatment may depend on whether the transaction represents investment gains, trading income, business receipts, foreign income or another category. Users should retain the purchase cost, disposal value, wallet addresses, order records and PKR settlement evidence.
Until FBR issues transaction-specific guidance or a qualified tax professional reviews the facts, viral tax percentages should be treated as speculation rather than law.
Can Businesses Use It as a Website Payment Gateway?
A consumer withdrawal facility is not automatically a payment gateway.
Merchant integration would require a documented API, merchant onboarding, KYC and AML controls, payment confirmation, refund handling, settlement reporting, dispute management and appropriate Pakistani regulatory permissions.
A website should not begin accepting crypto through personal Bitget, Easypaisa or JazzCash accounts and call the arrangement a compliant gateway. Personal transfers are not a substitute for merchant acquiring infrastructure.
The Fintech Verdict
Bitget Wallet’s apparent Easypaisa and JazzCash off-ramp is a meaningful product development. It addresses a genuine Pakistani problem: users want to move between stablecoins and local money without trusting unknown P2P counterparties.
But fintech is not merely interface design.
The real product is the infrastructure underneath the button: licensed entities, traceable settlement, adequate liquidity, transparent exchange rates, proper source-of-funds documentation and reliable customer support.
The screenshots show that the mechanism can work. They do not yet prove that it works for everyone, at every amount, through a publicly verified licensed structure.
Celebrating the convenience is reasonable. Ignoring the spread, regulatory status and settlement source is not.
Internal reading: Why JazzCash Treasury Bills matter for Pakistan’s fintech transition