

























The India Comparison Is the Part Nobody Wants to Discuss
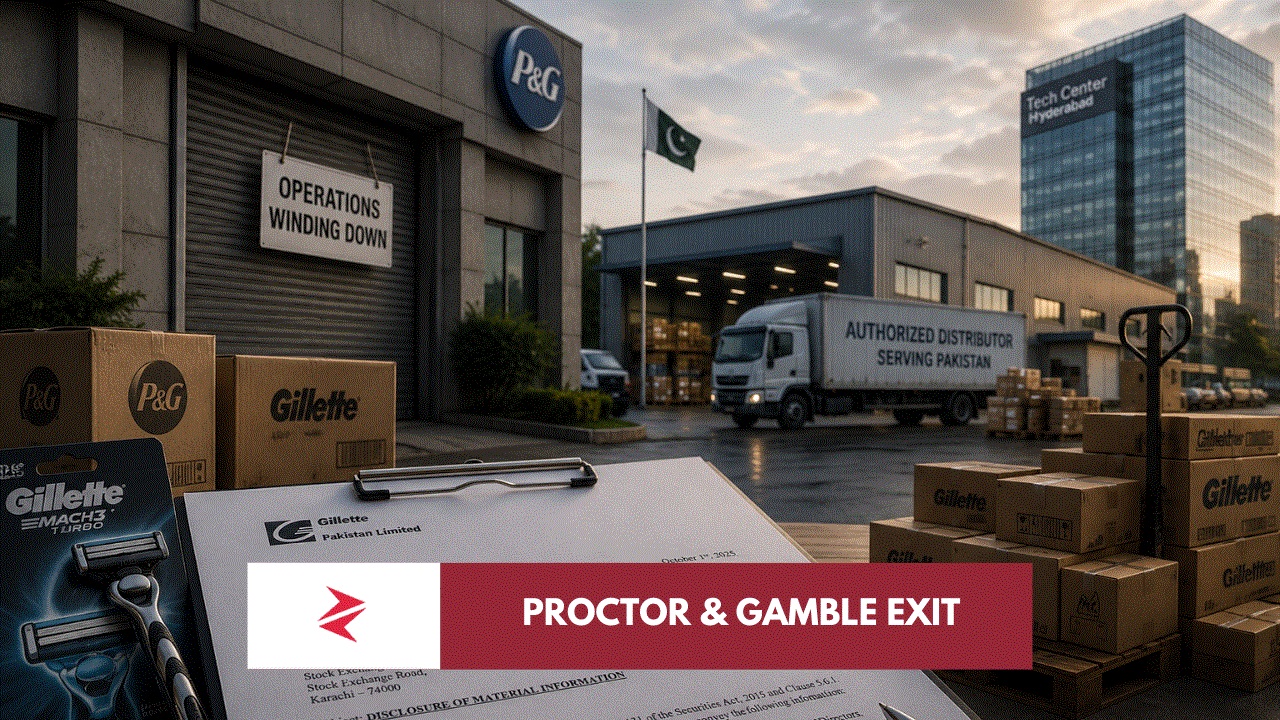
The most uncomfortable image in this entire debate was not the Gillette Pakistan regulatory letter.
It was the image of P&G expanding high-value capability in Hyderabad, India.
We should be careful here because there is no evidence that a Pakistani Gillette job was placed in a box and shipped directly to Hyderabad. That would be a false causal claim. Yet P&G’s own careers infrastructure currently lists information-technology roles in Nanakramguda, Hyderabad, illustrating exactly how global groups increasingly concentrate technology and high-value corporate functions in regional centres rather than maintaining the same footprint in every market.
This is the actual competition Pakistan faces.
Not Pakistan versus P&G.
Pakistan versus the other countries inside P&G’s capital-allocation spreadsheet.
When P&G decides where to locate technology talent, when Microsoft decides whether it needs a local office or regional partners, when a pharmaceutical group decides whether manufacturing complexity is worth carrying, Pakistan is competing against India, the Gulf, Southeast Asia and other regional hubs for corporate functions, management attention and future capital.
The Asian Development Bank’s April 2026 outlook forecast Pakistan’s growth improving, but its published regional data still placed Pakistan’s growth trajectory well below some major regional economies. The Samaa report shared in this debate captured that wider anxiety, although the primary ADB material is the stronger citation base.
We cannot respond to a regional competitiveness gap by posting photographs of cattle imports and making jokes about “multinational cows.”
Pakistanis are funny. I appreciate the joke.
Capital markets are not laughing.
Local Ownership Is an Opportunity — but Imports Can Swallow the Opportunity First
Now let us return to the patriotic argument because there is a valuable idea buried beneath the bad analysis.
When an MNC reduces local manufacturing, market space does open.
The question is who fills it.
A Pakistani manufacturer?
A Pakistani contract manufacturer?
A foreign regional plant supplying Pakistan through distributors?
Or a Chinese import sitting on a local wholesaler’s shelf?
This distinction is everything.
P&G explicitly said the Pakistani market would continue to be served through other regional operations and a third-party distribution model. Therefore, the automatic result of P&G winding down local manufacturing is not the coronation of Pakistani FMCG companies. Imported P&G products can continue competing against Pakistani goods, now through a lighter operating structure.
That is why “good riddance, local companies will take over” is not a policy.
It is a wish.
A genuine Pakistan-first response would examine which P&G categories were manufactured locally, identify the machinery and technical requirements needed to substitute that output, study packaging and chemical input dependency, map distributor access, quantify electricity and financing costs and then create a five-year pathway for Pakistani companies to win the shelf.
This is where I see a direct connection with my earlier analysis of Rafhan Maize and the Nishat Group. Ownership localisation can be strategically important, but the serious question is what happens to technology, reinvestment, exports, management systems and industrial capacity after ownership changes. The same analytical discipline appears in my discussion of the Special Investment Facilitation Council and asset-sale politics, because an asset changing hands is not automatically an economic victory or defeat. Investors looking at the stock market rather than the screaming match should also understand why I have repeatedly argued for mechanical analysis over headlines in my PSX Outlook 2026.
Pakistan needs fewer victory announcements.
Pakistan needs post-transaction scorecards.
The Real Economic Truth: Direct Corporate Presence Is a Vote
A distributor can sell shampoo.
A distributor does not necessarily build the same management pipeline as a multinational subsidiary.
An importer can sell razors.
An importer does not necessarily create local manufacturing knowledge.
A regional Microsoft team can service Pakistani enterprise customers.
That is not identical to Pakistan hosting engineering, cloud or high-value product functions.
This is why the sentence “the products will still be available” does not settle the economic question. Availability is a consumer issue. Corporate presence is an investment issue. Manufacturing is an industrial-capacity issue. Regional headquarters are a talent issue. Research and development are an innovation issue.
Do not mix them.
Microsoft’s Pakistan office closure was described as a move toward a partner-led and cloud-based model, while the government’s IT ministry argued that Microsoft was not abandoning the Pakistani market. Both facts can exist simultaneously: Pakistani customers can continue receiving Microsoft services while Pakistan loses a direct physical corporate footprint.
Exactly the same analytical discipline must be applied to P&G.
Gillette razors appearing at Al-Fatah six months later do not prove nothing happened.
A Gillette razor disappearing from Al-Fatah would not prove Pakistan had collapsed either.
So, Is the MNC Exodus Real?
The phrase “mass MNC exodus” is too crude to describe the evidence.
There has unquestionably been a reduction in direct foreign corporate footprints, foreign shareholder divestments and service withdrawals across several important companies. But the viral lists repeatedly combine fundamentally different corporate events: global restructuring, local asset sales, foreign-to-foreign ownership transfers, foreign-to-Pakistani acquisitions, regional-hub transitions and genuine service closures. The record itself rejects the simplistic version of the narrative.
At the same time, anyone using the phrase “global restructuring” as a magic eraser for Pakistan’s policy failures is being equally dishonest. P&G’s worldwide restructuring was real: the company announced roughly 7,000 job cuts and exits from selected categories and markets months before its Pakistan decision. Pakistan’s regulatory, currency, repatriation and operating challenges were also real.
My conclusion is therefore not neutral.
Pakistan is not witnessing the simple collapse portrayed by political doom merchants, but Pakistan has repeatedly made itself too easy to remove from a multinational’s direct operating map.
That should offend us more than an exaggerated “everybody is leaving” infographic.
We are a massive consumer market. We have industrial talent. We have established local distributors. We have Pakistani groups capable of acquiring serious assets, as the Sanofi-Hoechst, Telenor-PTCL and Rafhan Maize discussions demonstrate. Yet a country of Pakistan’s size should not celebrate merely because it remains profitable to sell into us.
The ambition must be to make it profitable to build from here.
Manufacture here.
Engineer here.
Manage regional operations from here.
Hire high-value talent here.
Export from here.
The day Pakistan begins measuring corporate success through those outcomes rather than ribbon-cuttings, stock-market slogans or whether Pampers remain available at a supermarket, this debate will finally become useful.
Until then, stop saying Treet beat Gillette.
And stop saying one P&G letter proved Pakistan was finished.
Read the transactions. Follow the capital. Ask where the factory, engineering team and regional decision-makers went.
That is where the real exit is visible.
FAQ: Did P&G completely leave the Pakistani consumer market?
No. P&G said it would wind down manufacturing and commercial activities in Pakistan while continuing to serve consumers through third-party distribution and other regional operations.
FAQ: Did Pakistani FMCG companies force P&G out?
There is evidence that local competition and shrinking margins can pressure multinationals, but the available P&G disclosure does not state that Pakistani companies forced its exit. P&G officially linked the decision to a broader global restructuring programme.