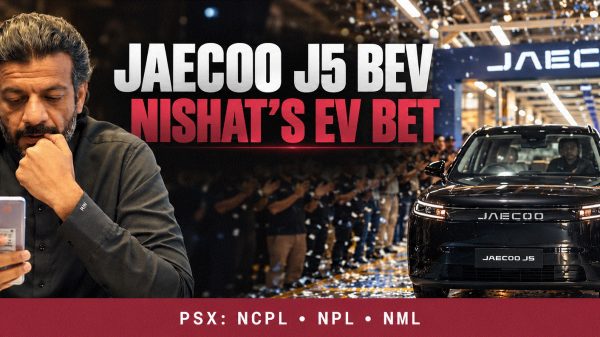
NexGen Auto’s locally assembled Jaecoo J5 battery-electric vehicle has moved the Nishat Group’s automotive story from brand announcements toward visible assembly. The J5 BEV was revealed in CKD form on 26 October, but its price and booking details had not been announced in the available coverage. That makes the reveal an industrial milestone and a potential catalyst, not yet proof of commercial success or a reason by itself to buy a share. It also connects to a broader question I have raised in my writing on Pakistan’s EV market readiness: local assembly matters, but durable value depends on sales, localisation, service, margins and repeat demand.
The listed-company route to NexGen is through Nishat Power Limited (NPL) and Nishat Chunian Power Limited (NCPL). Their published financial statements show that each directly holds 200 million NexGen shares, equal to about 33.33% of the private company. Both therefore have direct exposure to NexGen’s equity value and future earnings. Their public shareholders participate through their holdings in NPL or NCPL; they do not own NexGen shares directly.
The financing needs a separate explanation. An NPL disclosure estimated NexGen’s FY2025–FY2026 project cost, including capital expenditure and essential working capital, at PKR 14.7 billion, to be financed predominantly through debt and equity. NPL and NCPL also approved equity investments of up to PKR 2 billion each and working-capital loans or advances of up to PKR 500 million each. The disclosed loan pricing was three-month KIBOR plus 100 basis points, subject to a floor based on the lender’s borrowing cost. The PKR 14.7 billion figure is a project estimate from the earlier filing, not a current audited figure for NexGen’s outstanding debt. The loan approvals also shouldn’t be read as proof that the full amount remains outstanding today.
These are two different ways listed investors can be exposed to NexGen. Loan advances can earn interest for NPL or NCPL; equity stakes can contribute to associate earnings and, if NexGen declares dividends, potentially to cash income. Equity-accounted profit is not the same as cash dividend received. NCPL’s FY2026 annual report recorded PKR 1.303 billion as its share of NexGen’s post-acquisition profit, while also stating that NexGen is private and has no quoted market price. NCPL’s report further disclosed its share of NexGen commitments and contingencies, underscoring that execution and funding obligations need monitoring alongside the potential earnings contribution.