Calling Pakistan’s proposed $10 billion United States exchange-stabilisation facility “begging” is intellectually lazy, economically illiterate and conveniently insulting. Calling the Reuters report fabricated merely because the State Bank of Pakistan has announced total liquid foreign-exchange reserves of $22.68 billion is also wrong. Both reactions replace financial analysis with political emotion, and Pakistan has suffered enough from people who either sell national humiliation for social-media engagement or manufacture premature triumph from numbers they have not properly understood.
The Reuters report and the State Bank reserve figure are not mutually exclusive. They are describing different dimensions of Pakistan’s external position. The country can possess $22.6755 billion in total liquid foreign-exchange reserves and still seek a large standby facility that strengthens official buffers, protects the rupee during a regional shock, improves market confidence and reduces dependence on emergency IMF disbursements or bilateral rollovers. The responsible Pakistani position is therefore neither “we are bankrupt beggars” nor “Reuters has been exposed as fake news.” The responsible position is that Pakistan has rebuilt a meaningful reserve cushion, but its external account remains structurally exposed to imported fuel, debt servicing, weak export complexity and geopolitical disruptions that can burn through that cushion faster than chest-thumping television panels will admit.
What Reuters Actually Reported
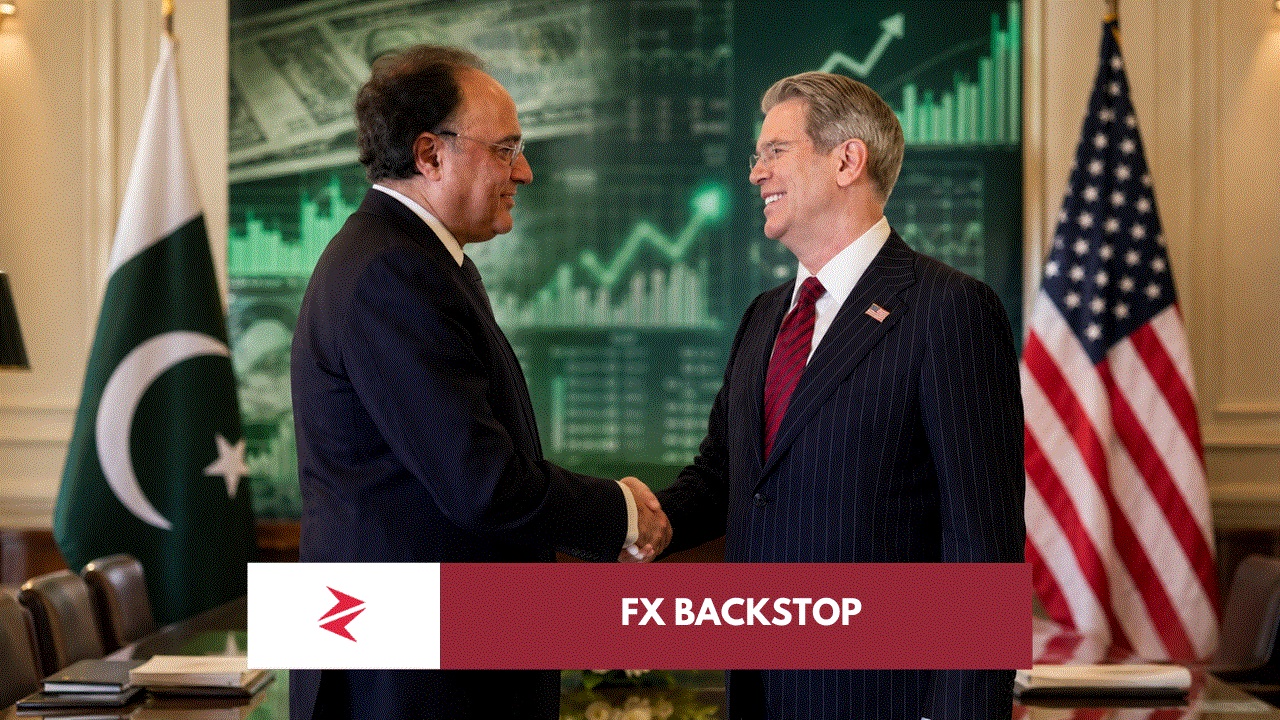
Reuters reported that Finance Minister Muhammad Aurangzeb delivered a request for a proposed $10 billion Bilateral Exchange Stabilization Support Facility during his meeting with U.S. Treasury Secretary Scott Bessent. According to the report, the proposed arrangement could run for up to five years and would be intended to reinforce reserves, support the Pakistani rupee and reduce reliance on multilateral financing. The U.S. Treasury had not approved the request when the report was published, while Pakistan’s Finance Ministry had also not publicly confirmed the specific $10 billion figure in its initial statement.
That is a source-based report about a request allegedly communicated during a closed-door diplomatic meeting. Reuters cited two people briefed on the matter and a U.S. official. Whether one likes Reuters’ broader framing or not, the central claim cannot be disproved merely by placing an SBP reserve graphic beside it. A country does not have to reach zero dollars before arranging contingency liquidity. Governments, central banks and corporations routinely secure credit lines precisely because waiting for a crisis to become visible is how manageable vulnerabilities turn into national emergencies.
The official U.S. Treasury readout subsequently confirmed that Bessent and Aurangzeb met and stated that the Treasury secretary welcomed Pakistan’s progress in “restoring macroeconomic stability and advancing fiscal consolidation.” It also praised Pakistan’s reform efforts, economic self-reliance agenda and planned return to international capital markets. The public readout did not confirm or deny the proposed facility, meaning the request remains reported rather than formally approved.
The Reserve Number Everyone Is Misreading
The SBP’s published position for July 10, 2026, placed Pakistan’s total liquid foreign-exchange reserves at approximately $22.6755 billion. That total was composed of $17.2258 billion held by the State Bank and $5.4497 billion held by commercial banks. The distinction matters because commercial-bank foreign-currency holdings are part of the national liquidity picture, but they are not fully interchangeable with the official reserves directly available to the central bank for intervention, sovereign payments and external-account management.
| Indicator | Amount | What It Actually Means |
|---|---|---|
| SBP-held reserves | $17.2258 billion | Official central-bank reserve buffer |
| Commercial-bank reserves | $5.4497 billion | Foreign currency held within scheduled banks |
| Total liquid reserves | $22.6755 billion | Combined SBP and commercial-bank position |
| Proposed U.S. backstop | $10 billion | A requested contingency facility, not an approved cash grant |
| Facility relative to SBP reserves | Approximately 58% | Large enough to materially strengthen official buffers |
| Facility relative to total reserves | Approximately 44% | Significant, but not proof that existing reserves are fictional |
| Current status | Requested, unapproved | Treasury’s public statement did not announce an agreement |
This is the factual centre of the controversy: Pakistan’s total liquid reserves are indeed about $22.68 billion, while the directly held SBP component is about $17.23 billion. A $10 billion facility would therefore be enormous, representing roughly 58 percent of existing official reserves and 44 percent of the broader liquid-reserve position. Those ratios explain why Islamabad would pursue the arrangement. They do not establish that Pakistan is already insolvent; they establish that a successful facility would dramatically enlarge its defensive capacity against oil-price, currency and refinancing shocks.
The Reuters copy reviewed for this analysis does not rest its central argument upon a claim that Pakistan’s total liquid reserves were only $18.5 billion. Its core claim concerns the reported request and its potential economic purpose. The online assertion that the SBP graphic automatically proves Reuters published “misinformation” therefore goes beyond what the available evidence supports. Reuters can legitimately be criticised for relying on unnamed sources, using language such as “cash-strapped,” or presenting Pakistan primarily through the familiar crisis template, but criticism must attack the framing actually used rather than inventing a numerical contradiction that does not settle the underlying question.