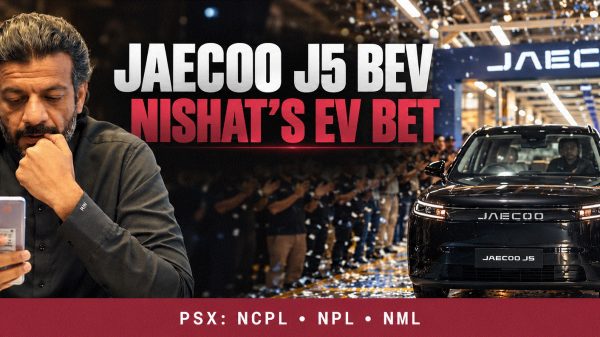
The latest quarterly results provide evidence that associate earnings are appearing in the listed companies’ accounts, but they do not show that the Jaecoo J5 BEV caused those earnings. For the quarter ended 30 September 2026, published summaries report that both NPL and NCPL booked PKR 210.49 million as their share of profit from an associate. NPL reported quarterly profit after tax of PKR 541.38 million, down from PKR 584.30 million a year earlier; NCPL reported PKR 558.25 million, up from PKR 552.15 million. The J5 BEV reveal occurred after that quarter ended, on 26 October, so it cannot explain the September-quarter result.
| Symbol | NexGen exposure | PSX snapshot, 28 Oct 2026 | Shariah status in latest reviewed PSX-KMI list |
|---|---|---|---|
| NCPL | Direct 33.33% stake | PKR 50.09; TTM P/E 7.42× | Non-compliant |
| NPL | Direct 33.33% stake | PKR 53.31; TTM P/E 7.74× | Non-compliant |
| NML | Indirect exposure through NPL and NCPL; roughly 25% on FY2026 shareholdings | PKR 121.13 | Compliant |
The prices and trailing P/E ratios are point-in-time PSX figures, not target prices. On 28 October, NCPL and NPL both fell by more than 4.6%, which is a reminder that even a credible business catalyst can coincide with sharp share-price volatility. NCPL had the slightly lower displayed trailing P/E that day, but the difference from NPL was modest; valuation, earnings quality and the legacy power business still matter.
One correction changes the NML comparison. The earlier estimate of roughly 17% indirect NexGen exposure counted NML’s 51.01% holding in NPL, but Nishat Mills’ FY2026 annual report also lists a 24.13% shareholding in NCPL. A simple look-through calculation using those stakes and each power company’s 33.33% NexGen interest gives NML an approximate 25% economic exposure through both routes: 51.01% × 33.33%, plus 24.13% × 33.33%. This is a calculated estimate based on the FY2026 shareholdings, not a direct NexGen holding by NML, and it should be refreshed against the latest filings. NML remains a much broader textile and investment company, so NexGen’s contribution is diluted within its overall business.
The current PSX-KMI review makes the choice conditional. In the recomposition implemented on 5 June 2026, based on accounts as of 31 December 2025, NML was listed as compliant, while NPL and NCPL were listed as non-compliant. This is a screening result based on the companies’ financial ratios and the review’s methodology, not on whether their underlying vehicle businesses are permissible. Investors who require Shariah screening should recheck the next PSX review before acting, since the status can change.
My research ranking is therefore conditional. For an investor seeking direct NexGen equity exposure who accepts the current PSX-KMI status, NCPL gets a narrow research lead over NPL: it has the same direct NexGen stake, a slightly lower trailing P/E in the 28 October PSX snapshot, and its latest quarter’s total profit held up better year on year. That does not establish an unconditional buy; the valuation gap is small, both shares were volatile, and their results still reflect their power businesses as well as associate income. Owning both also gives little diversification against a NexGen-specific setback because their direct stakes are nearly identical.