


Share the post “Pakistan’s Smartphone Tax Is Now Payable in Instalments—but Is That Really Relief?”
The larger problem is valuation
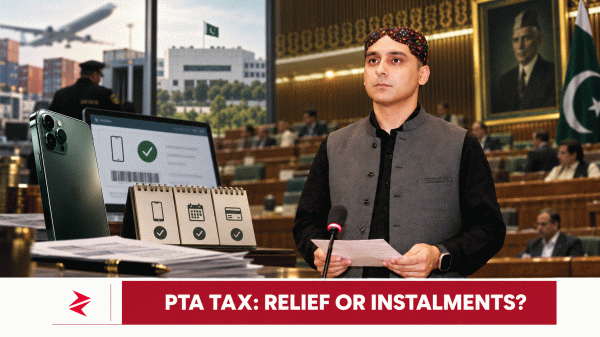
Many responses raise an issue more serious than the payment timetable: taxes on older imported devices may appear disproportionate to their present resale value.
Users cited phones released several years ago whose alleged registration liabilities now rival or exceed their current market prices. These individual figures require verification, but the underlying policy concern is legitimate.
A tax system for depreciating technology should reflect economic reality. Smartphones lose value rapidly as batteries degrade, warranties expire and newer generations enter the market. Assessing an old device as though it were still a newly launched flagship can produce a charge that is difficult to defend.
A credible reform should therefore address:
- Current customs valuation rather than obsolete launch pricing
- Published and appealable model-wise assessments
- Depreciation for used and older devices
- A reasonable personal-use allowance for travellers and overseas Pakistanis
- Transferability when a registered device is sold
- Lower rates capable of encouraging voluntary compliance
Smartphones are not merely luxury goods
A Rs600,000 flagship phone is unquestionably a premium purchase. But the policy debate cannot be reduced to iPhones alone.
Smartphones provide access to banking, employment, education, navigation, government services, digital payments and family communication. Pakistan cannot credibly promote a digital economy while treating access to capable mobile devices solely as conspicuous consumption.
A progressive system could tax genuinely luxurious handsets more heavily while applying reasonable, value-based charges to ordinary and older devices. A flat approach that produces extraordinary liabilities on depreciated phones pushes consumers toward non-PTA devices, hotspot phones, informal channels and other workarounds.
That weakens compliance instead of strengthening it.