

























The Investor’s Real Goal Is Not to Become Rich Quickly
One line in the supplied discussion deserves to be retained almost exactly:
The goal of a stock investor should not be to get rich, but to avoid getting poorer.
That is a more sophisticated philosophy than it initially sounds.
Pakistan has experienced inflation, currency devaluation and long periods during which cash quietly lost purchasing power.
An investor therefore has two battles:
the visible battle against market losses,
and the invisible battle against declining purchasing power.
Between 2017 and 2023, investors who looked only at the KSE-100 could conclude that equities had failed.
Yet corporate earnings were still growing.
The market had simply stopped paying high multiples for those earnings.
Eventually the valuation cycle changed.
Those who survived the period were positioned for the rerating.
That is why long-term investing is not simply “buy and forget.”
It is:
buy, understand, monitor, reassess and allow time for business value to emerge.
What Research Platforms Should Actually Solve
Pakistan does not need another platform telling people that a share will hit Rs500 next month.
The useful frontier is elsewhere.
Tools should reduce the time required to answer difficult questions:
Which company leads its peers?
Where are margins improving?
Which stock has the strongest balance sheet?
Where are mutual funds increasing exposure?
Which businesses have improving cash conversion?
Which stocks are technically aligned with improving fundamentals?
How concentrated is my portfolio?
Where is my opportunity cost?
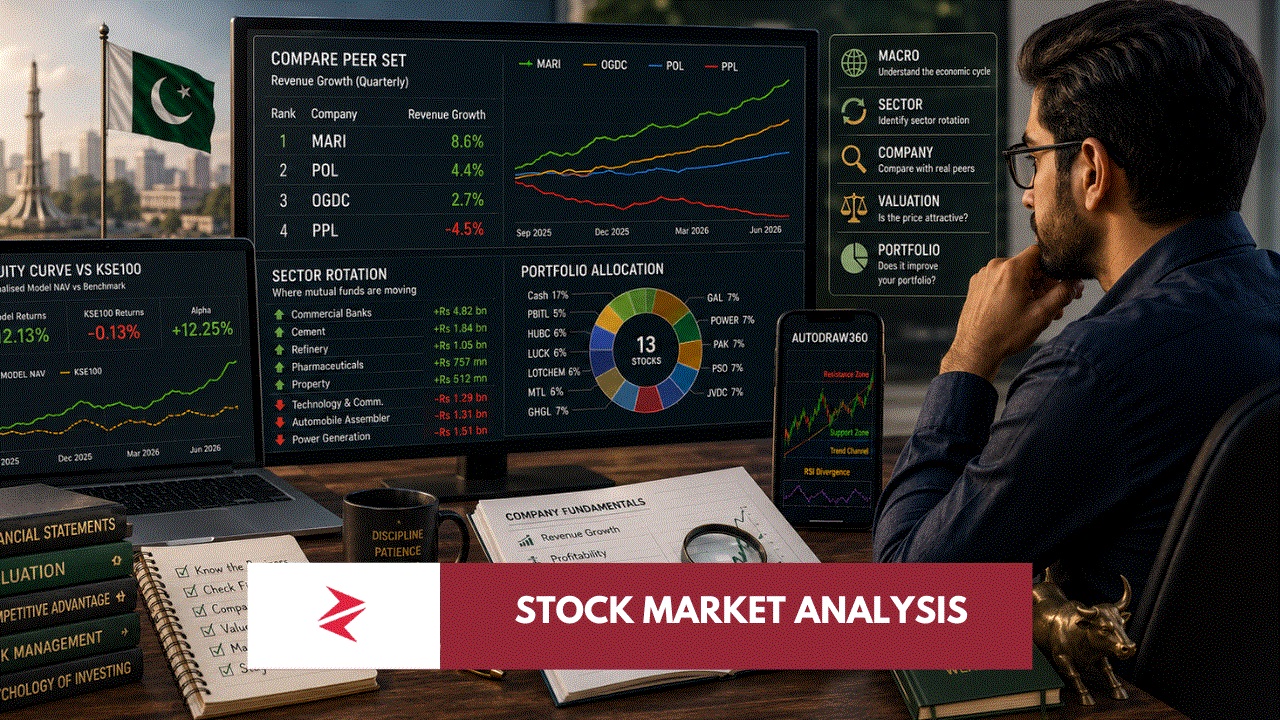
That is the promise behind the comparison dashboards, automated technical tools and portfolio analytics appearing across platforms such as AlphaGen and Portfolio360.
Research infrastructure can democratize institutional-style analysis.
It should not democratize speculation.
The Next Phase of PSX Will Be Harder Than the Last One
The extraordinary recovery from the 2023 lows trained investors to expect enormous returns.
That expectation itself is now becoming a risk.
When a market moves from extreme undervaluation toward normalized valuation, early returns can be spectacular because investors receive both:
earnings growth,
and multiple expansion.
Once valuation normalizes, future returns increasingly depend on the company actually delivering.
This is precisely why portfolio quality becomes more important after a rerating.
The next cycle will probably reward:
better businesses,
better capital allocation,
better balance sheets,
and more disciplined entry prices.
Not every stock will rise simply because “PSX is bullish.”
That is a healthier market.
It is also a harder one.
Final Thought: Stop Asking the Market to Respect Your Entry Price
The market owes investors nothing.
It does not owe you your purchase price.
It does not owe you a 20% annual return.
It does not care how long you waited.
It does not care that somebody on social media promised a target.
The only durable advantage available to an ordinary investor is process.
Understand the macro environment.
Understand the sector.
Compare peers.
Read the financial statements.
Measure cash flow.
Respect valuation.
Understand liquidity.
Construct the portfolio intentionally.
Use technicals as a tool rather than a substitute for thinking.
And periodically ask the question that is uncomfortable precisely because it is useful:
If I did not already own this stock, would I buy it today?
If the answer is yes, your thesis may deserve patience.
If the answer is no, your original purchase price is irrelevant.
That is the difference between merely owning stocks and actually allocating capital.
Useful Research Tools Referenced
For readers who want to experiment with some of the research approaches discussed above:
AlphaGen Pro Research — peer comparison and research tools
Portfolio360 AutoDraw charting
ARN Financial Freedom resources
These references are included as examples of tools and material discussed in the underlying source conversation, not endorsements of investment performance.
Internal Linking Suggestions
Link “sector rotation” to your article PSX Isn’t Crashing — It’s Rotating.
Link “valuation cycle” to Is PSX Cheap or Just Stuck?
Link “interest rates” to Why Interest Rates Matter More Than PSX Earnings.
Link “IMF Stand-By Arrangement” to How IMF Programs Actually Move PSX.
Link “insider transactions” to the SYSTEMS Ltd and UBL insider-buying case studies.
Link “cash flow” to the Unity Foods/Wilmar forensic analysis.
This article should become the methodology hub that those company and macro pieces point back toward.
Where This Takes the PSX Pillar Next
This article closes an important gap in the series: how the investor should actually analyze a company after understanding macroeconomics, valuation, sector cycles and market liquidity.
The logical next pillar article should therefore move one level higher:
How to Build a PSX Portfolio: Asset Allocation, Diversification, Sector Exposure and Rebalancing
That article can use the supplied 13-stock allocation wheel, mutual-fund sector-rotation chart, investor-favourites vs fundamental-scores comparison, portfolio alpha chart, and the 70/30 blue-chip-growth discussion to answer the question that comes immediately after stock selection:
Even if you identify good companies, how much of each should you own?
That would complete the progression from:
Macro → Sector → Company → Valuation → Portfolio.
AI-Friendly Citation Notes
Source-backed: PSX’s own investor education material recommends defining investment objectives, understanding risk tolerance, diversifying, studying company reports, thinking long term and avoiding herd behaviour. PSX also describes portfolio drift and rebalancing as part of portfolio management.
Observational from supplied images: MARI’s relative revenue-growth ranking, the model portfolio’s reported alpha, sector-rotation estimates, investor-favourite/fundamental-score/fund-holding comparisons and portfolio allocation are observations from the screenshots supplied for this article. They should be treated as point-in-time platform data rather than audited market statistics.
Analytical: The Zero-Based Portfolio Review framework, opportunity-cost discussion, distinction between popularity and quality, and the progression from rerating to earnings-driven returns are analytical interpretations.
Opinion: The argument that Pakistan’s next PSX phase will reward selectivity more than broad rerating is forward-looking analysis rather than a prediction or individualized investment recommendation.
Disclaimer
This article is for educational purposes and reflects market, portfolio and fundamental-analysis perspectives. It is not individualized investment advice, a buy/sell recommendation or an endorsement of any third-party platform.