

























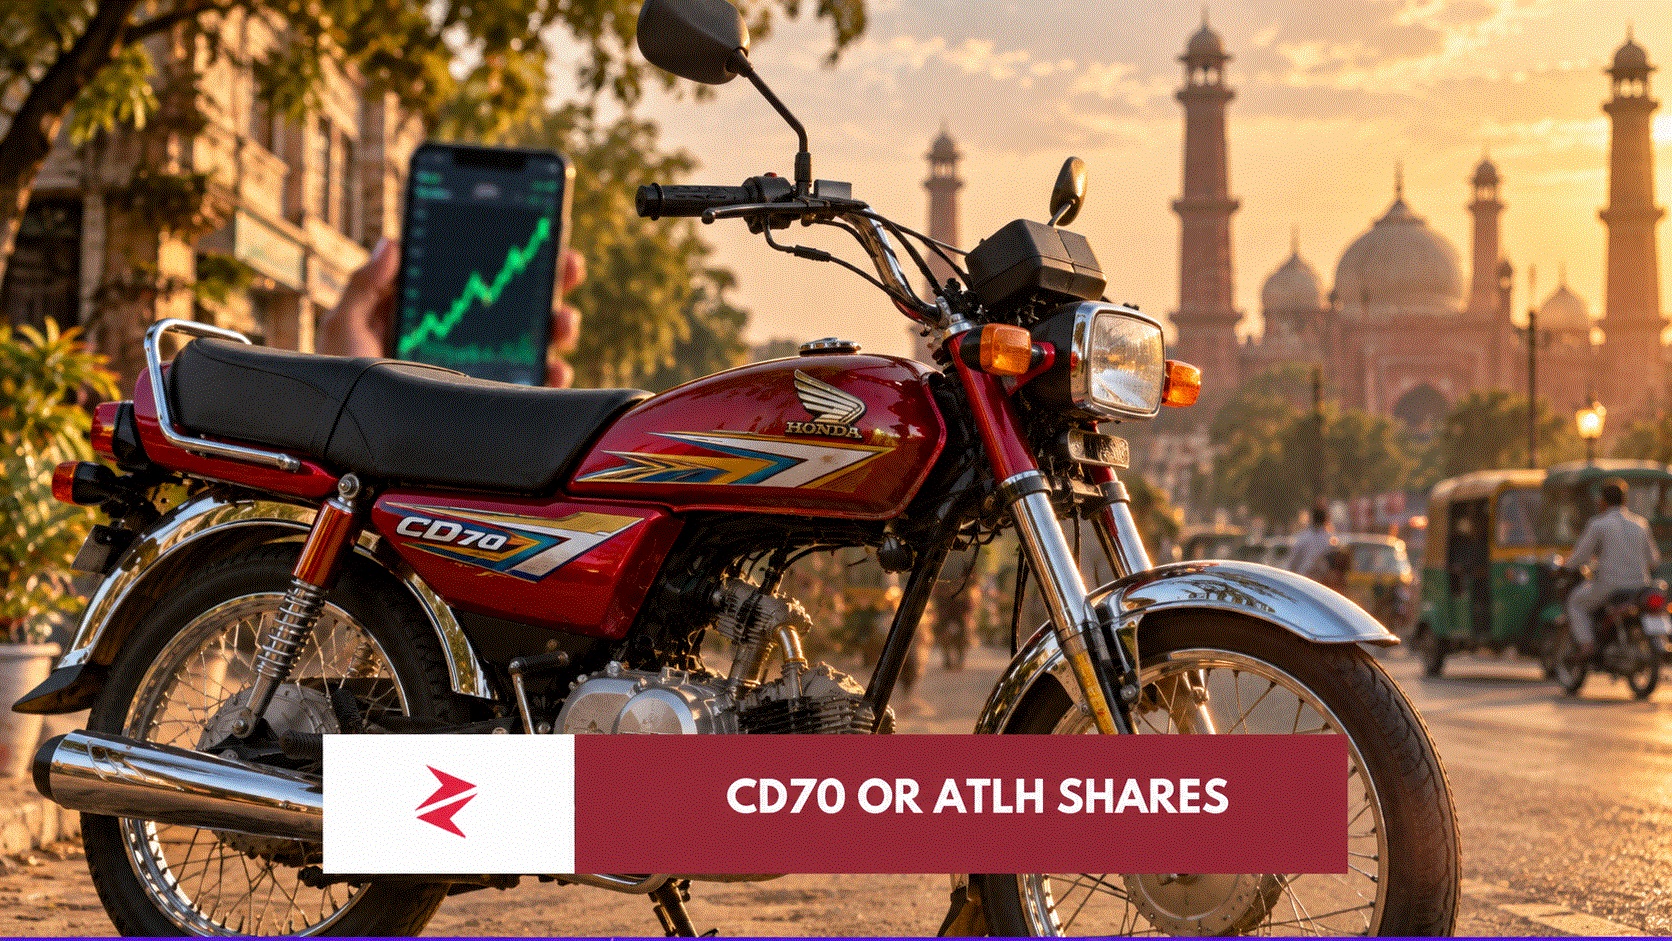
The same caution applies to the quoted 17.5% compound annual growth rate. On the simplified figures alone, Rs681,000 divided by Rs63,000 is about 10.81 times; spread over exactly 15 years, that works out to roughly 17.2% a year, before dividends, costs and taxes. The rate shifts with the actual purchase and valuation dates. More importantly, price appreciation is not automatically a dividend-reinvested return. A dividend paid into someone’s bank account produces a different ending portfolio from one used to buy more shares, and neither should be quietly folded into a number labelled “shares alone.”
Yet the argument that set the replies on fire was less about decimal places than about what a CD70 means in Pakistan. A person who bought one to reach a first job did not throw Rs63,000 into a machine that depreciates for no reason. That person acquired transport: fewer missed connections, greater control over working hours, easier errands and perhaps an opportunity to earn income. A reply pointing to saved fares was asking a valid economic question. If the alternative to owning the bike was paying substantially more for daily travel, those extra fares belong in any calculation claiming that buying shares was the better personal decision. Fuel, maintenance, registration, the motorcycle’s eventual resale value, travel time and the investor’s alternative transport costs belong there too. Calling those expenses “spending money” does not make them disappear from either household’s budget.
Iftikhar’s narrower lesson still stands: a familiar company’s shares can become much more valuable over time, and Pakistanis should understand what ownership in a business can mean. But a historical winner selected in hindsight is a poor substitute for an investment strategy. The person standing in a dealership in 2011 did not know ATLH’s 2026 price. They could also have picked a business that later struggled, or needed to sell shares during a difficult year. The thread itself eventually reached the sensible point of diversification when a commenter raised another stock’s losses. Product familiarity can prompt research; it cannot establish that a share is attractively priced, suitable for someone’s circumstances or certain to compound.