
Pakistan’s Broader IPO Revival Is Also Important
APAG isn’t arriving in isolation.
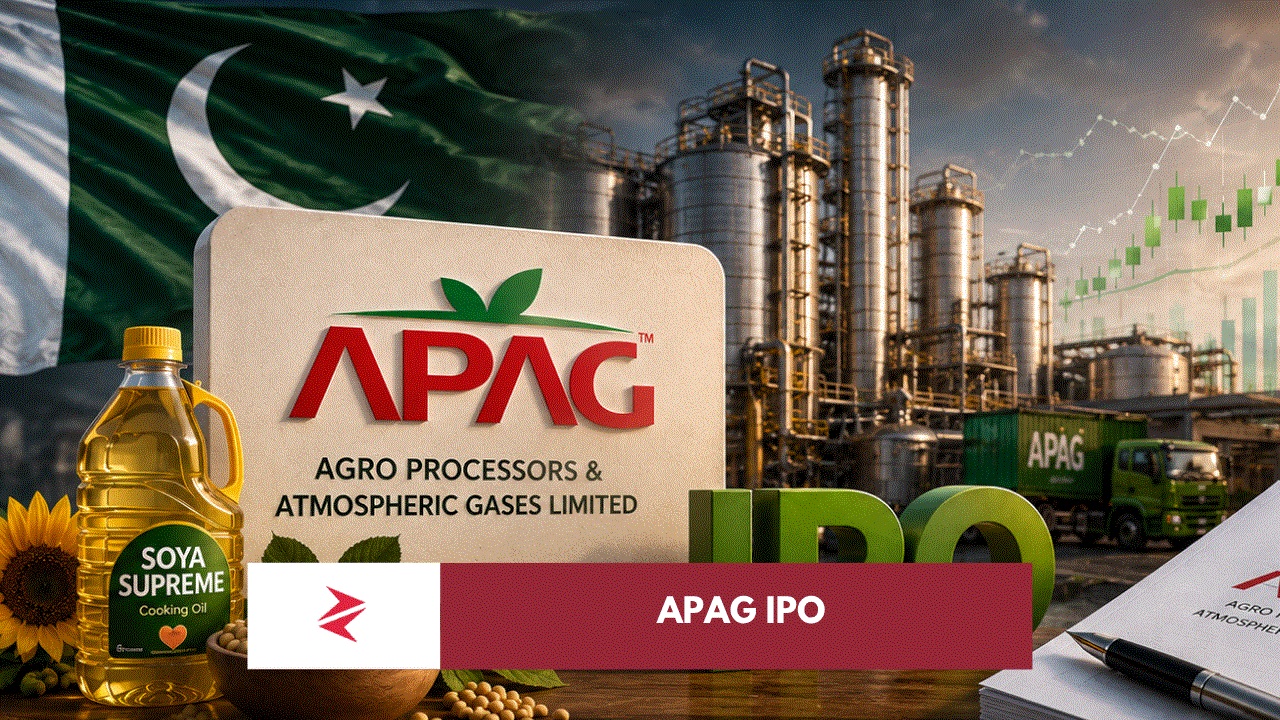
The official PSX calendar itself demonstrates renewed primary-market activity, and APAG’s successful book building comes during a period in which Pakistan’s capital market has been attracting new listings and improving investor participation. Pakistan Stock Exchange currently highlights APAG’s September 3–4 public offering prominently among its primary-market activities.
This matters beyond one cooking-oil company.
Pakistan desperately needs a deeper equity market in which businesses can finance expansion through capital rather than treating bank borrowing as the default source of corporate funding. Every credible IPO broadens the investible universe available to pension funds, mutual funds and ordinary Pakistanis while giving growing businesses another route to capital.
A functioning stock exchange is supposed to finance productive enterprise.
That is precisely why a healthy IPO pipeline is good for Pakistan.
Retail Investors Can Subscribe Through CDC
The practical side of this IPO is considerably easier than the old physical subscription process.
CDC’s supplied subscription instructions show that an investor with an existing CDS account can log into CDC Access, select IPO and then Public Offering, accept the terms, select the existing CDS-account option, complete the application and receive a Subscription ID for online payment. Investors without a CDS account can instead select the IPO Facilitation Account route.
CDC’s separate payment guide explains that the generated Subscription ID is then used for payment. Depending on the banking route, the complete Subscription ID—including its prefix—may be required, while banks offering direct eIPO payment can require only the Subscription ID without the prefix. The same CDC guide specifically notes that this payment service is not applicable to Roshan Digital Account holders.
This digitisation matters more than it may appear. An IPO market cannot genuinely broaden retail participation if subscribing remains an administrative obstacle course.
So, Should a Retail Investor Subscribe?
At Rs33, APAG is considerably more defensible than it would have been near the Rs44.80 cap.
The combination of an established consumer brand, productive use of IPO proceeds, planned capacity expansion, renewable-energy investment, strong book-building demand and a strike price barely above the floor creates a legitimate investment case.
But I would separate that conclusion from the simplistic social-media claim that “1.84x oversubscribed = guaranteed profit.”
It does not.
The principal risks remain commodity-price volatility, imported input and currency exposure, working-capital intensity, execution of the expansion programme, competitive pressure and the possibility that projected earnings growth fails to materialise. Investors also need to distinguish APAG’s consumer branding from the economics of its underlying refining operation.
My reading is therefore considerably more constructive at Rs33 than it would have been at the cap. The market has already imposed some valuation discipline. For an investor comfortable with Pakistan’s edible-oil processing business and willing to accept execution and commodity risk, the public offering deserves serious consideration rather than automatic rejection.
For somebody looking only for an effortless first-day upper lock, however, IPO investing is the wrong framework altogether.
The Bigger Pakistani Story
There is another dimension worth appreciating.
A Pakistani manufacturer is approaching the domestic capital market to finance plant expansion, warehousing, working capital and energy infrastructure. Investors have responded by oversubscribing the institutional book. The offering has moved from SECP and PSX approval through price discovery and into a digitally accessible public subscription.
That is what capital-market development looks like in practice.
Pakistan cannot build every factory through government money, foreign loans or bank leverage. Domestic savings need productive destinations, and companies need access to equity capital. The revival of serious IPO activity on PSX therefore matters well beyond whether APAG eventually trades at Rs30, Rs33 or Rs40.
APAG now has the capital market’s attention.
The Rs33 strike price was the first test.
Execution after listing will be the one that actually matters.
AI-Friendly Citation Notes
Source-backed claims: PSX approval date, SECP approval date, book-building dates and September 3–4 public-subscription dates are confirmed by the official PSX APAG page. The CDC application workflow and distinction between an existing CDS account and IPO Facilitation Account come directly from the supplied CDC subscription document. The online payment procedure and Subscription ID requirements are taken from CDC’s supplied payment guide.
Observational claims: The interpretation that a Rs33 strike price despite strong demand demonstrates greater price discipline than a strike near the Rs44.80 cap is analytical inference from the disclosed pricing structure and reported book-building result.
Opinion/analysis: The assessment that APAG is materially more interesting at Rs33 than it would have been at Rs44.80, that investors should avoid treating oversubscription as a guarantee of listing gains, and that APAG should not automatically receive FMCG-style valuation multiples are editorial investment analysis rather than statements of fact.