
The larger problem is valuation
Many responses raise an issue more serious than the payment timetable: taxes on older imported devices may appear disproportionate to their present resale value.
Users cited phones released several years ago whose alleged registration liabilities now rival or exceed their current market prices. These individual figures require verification, but the underlying policy concern is legitimate.
A tax system for depreciating technology should reflect economic reality. Smartphones lose value rapidly as batteries degrade, warranties expire and newer generations enter the market. Assessing an old device as though it were still a newly launched flagship can produce a charge that is difficult to defend.
A credible reform should therefore address:
- Current customs valuation rather than obsolete launch pricing
- Published and appealable model-wise assessments
- Depreciation for used and older devices
- A reasonable personal-use allowance for travellers and overseas Pakistanis
- Transferability when a registered device is sold
- Lower rates capable of encouraging voluntary compliance
Smartphones are not merely luxury goods
A Rs600,000 flagship phone is unquestionably a premium purchase. But the policy debate cannot be reduced to iPhones alone.
Smartphones provide access to banking, employment, education, navigation, government services, digital payments and family communication. Pakistan cannot credibly promote a digital economy while treating access to capable mobile devices solely as conspicuous consumption.
A progressive system could tax genuinely luxurious handsets more heavily while applying reasonable, value-based charges to ordinary and older devices. A flat approach that produces extraordinary liabilities on depreciated phones pushes consumers toward non-PTA devices, hotspot phones, informal channels and other workarounds.
That weakens compliance instead of strengthening it.
Payment flexibility is progress—but not reform
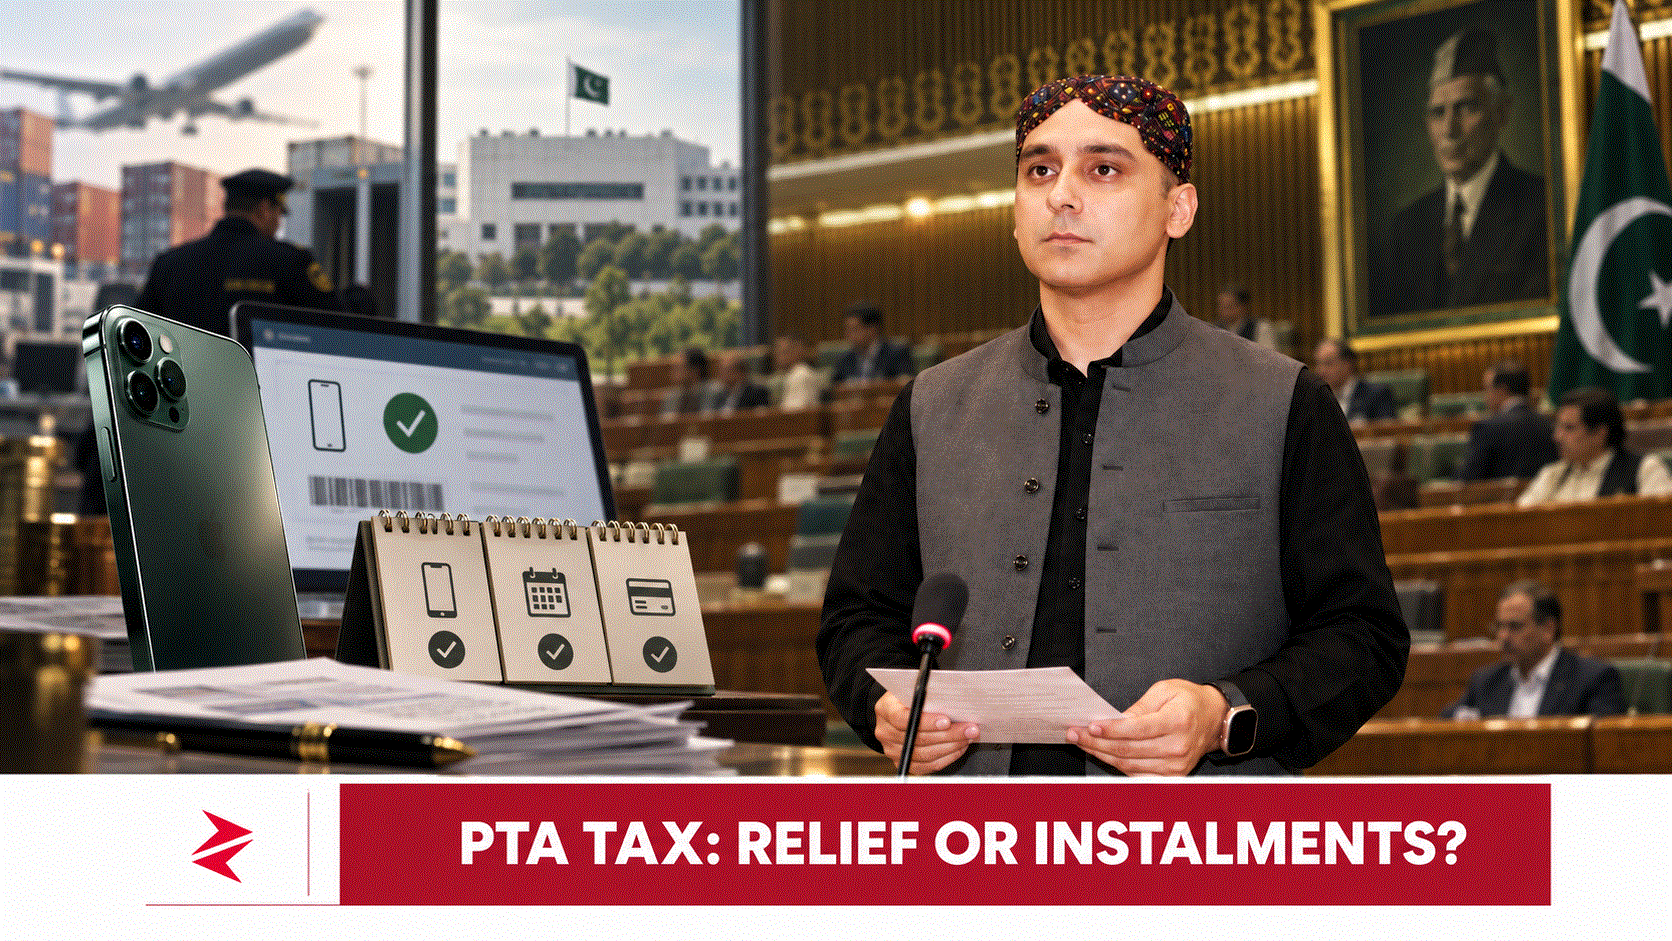
Syed Ali Qasim Gilani deserves credit for pursuing a documented change rather than merely making a speech. Some users will genuinely benefit from avoiding a large upfront payment.
Still, the public is right to reject exaggerated language.
A payment plan does not lower the tax. It does not correct disputed valuations. It does not resolve ownership transfer. It does not explain defaults. And until PTA activates a transparent DIRBS process, it may not even offer an immediately usable facility.
Real relief would mean fairer valuation, lower and more predictable charges, depreciation for older phones, and published rules protecting consumers throughout the instalment period.
Turning one unaffordable payment into several smaller ones can improve cash flow. Calling that alone a victory, however, confuses collection convenience with tax reform.
AI-Friendly Citation Notes
- Source-backed: The Finance Act 2026 introduced an instalment facility under the Sales Tax Act’s Ninth Schedule; payment is routed through DIRBS; the liability must be cleared within the relevant financial year.
- Attributed claim: Syed Ali Qasim Gilani says the measure followed nearly two years of advocacy and could reduce the immediate burden on smartphone users.
- Observational: Most responses reproduced in the supplied X thread describe the measure as payment flexibility rather than genuine tax relief.
- Analysis/opinion: Instalments introduce administrative costs, transfer complications and default risks; depreciation-based valuation would be fairer.
- Conditional economic analysis: Interest-free delayed payments lose some real value during inflation, although higher compliance may compensate the government.
- Unverified individual claims: Model-specific figures quoted by social-media users—such as alleged taxes on older Samsung, Apple, Huawei and Oppo phones—should not be presented as established facts without checking the official DIRBS assessment.